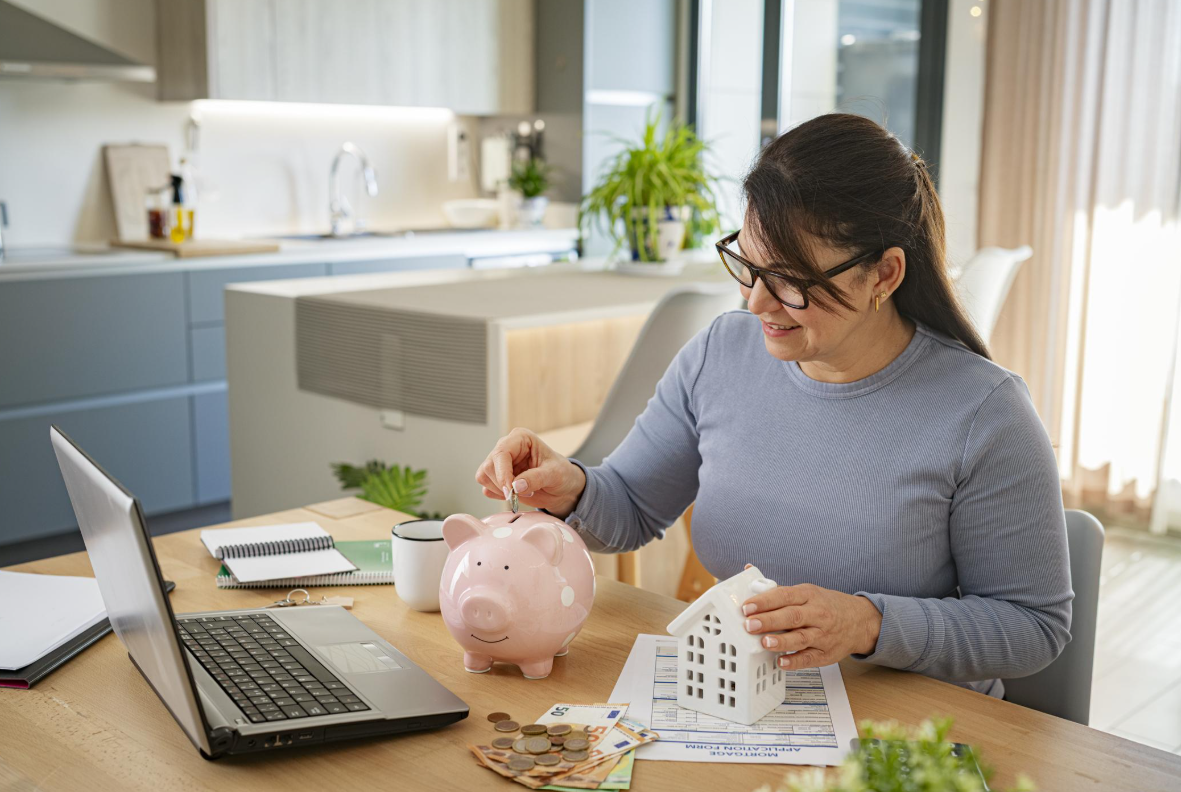
Buying a home is more than finding the right property. It is also about preparing yourself financially, developing good money habits, and understanding the responsibilities that come with homeownership. For many people, purchasing a home represents an important personal milestone. However, reaching that goal often requires patience, planning, and consistent effort. Developing healthy financial habits can help make the process less stressful and prepare you for the responsibilities of owning a property. Start by identifying what you want to achieve. Are you hoping to purchase your first home, move into a larger property, or find a home that better supports your lifestyle? Having a clear goal makes it easier to establish a timeline and determine how much money you may need. Break your larger objective into smaller steps, such as saving for a down payment, reviewing your credit, and researching mortgage options. Saving for a home requires more than setting aside money for a down payment. Buyers should also plan for closing costs, moving expenses, initial repairs, furnishings, and an emergency fund. Review your monthly spending and identify areas where you can save. Setting up automatic transfers to a dedicated savings account can help build consistency. Even smaller contributions can add up over time. Your credit history and overall financial profile can influence the mortgage options available to you. Review your credit reports for errors, make payments on time, and manage outstanding debt responsibly. Avoid taking on unnecessary new debt before applying for a mortgage. Large purchases or significant financial changes during the loan process may affect your qualification. If you have questions about your credit or loan eligibility, consider speaking with a qualified financial or mortgage professional. A realistic budget helps you understand how much you can comfortably spend on housing. Consider your regular income, existing debt, transportation costs, groceries, insurance, savings, and other monthly obligations. Remember that homeownership includes expenses beyond the mortgage payment. Property taxes, insurance, utilities, maintenance, and unexpected repairs should all be part of your financial planning. A budget based on your actual spending habits can help prevent financial pressure later. It is easy to become excited when you find a property that matches your preferences. However, making a major financial decision under pressure can lead to unnecessary stress. Take time to compare properties, review costs, and understand the terms of a potential mortgage. Do not feel obligated to purchase a home simply because other people are moving forward with their plans. Your financial situation and personal timeline should guide your decision. Learning about mortgages, property taxes, insurance, closing costs, and real estate transactions can help you feel more prepared. Use reliable educational resources, ask questions, and speak with qualified professionals when you need clarification. The more you understand about the process, the easier it becomes to recognize potential costs and evaluate your options. Financial preparation should not stop once you purchase a home. Continue saving regularly, monitor household expenses, and maintain an emergency fund for unexpected repairs or changes in income. Developing these habits can help you manage the ongoing responsibilities of homeownership and work toward other financial goals. Personal development often begins with small, consistent actions. Improving your financial habits, learning about real estate, and setting realistic goals can help you prepare for homeownership. You do not need to accomplish everything at once. Focus on steady progress and make decisions that support your financial well-being. With preparation, patience, and the right guidance, your homeownership goals can become a more achievable part of your long-term plans.1. Set Clear and Realistic Homeownership Goals
2. Develop Consistent Saving Habits
3. Understand Your Credit and Financial Position
4. Learn to Create and Follow a Budget
5. Practice Patience and Avoid Emotional Decisions
6. Invest in Your Financial Knowledge
7. Build Habits That Support Long-Term Stability
Take Small Steps Toward a Bigger Goal
Building Financial Confidence Before Buying a Home: Habits That Support Your Goals